

Since mid-August, Southeast gas prices have traded at ~$3.75-7.50/MMBtu, even as Henry Hub prices have held at ~$2.75-3.00. Prices at SoNat, FGT Zone 3, Transco between Stations 65 and 165, and TGP 500L reflect pipeline constraints into the region and storage inventories drained by heat that lasted into September.
Storage is now so low that I expect pipelines into the region to run near capacity through the end of winter. Basis differentials will remain in the $0.50-1.00/MMBtu range, with heightened risk of spikes to $2+/MMBtu. New pipelines under construction will ease these constraints over the next year.
Where and why have prices been high?
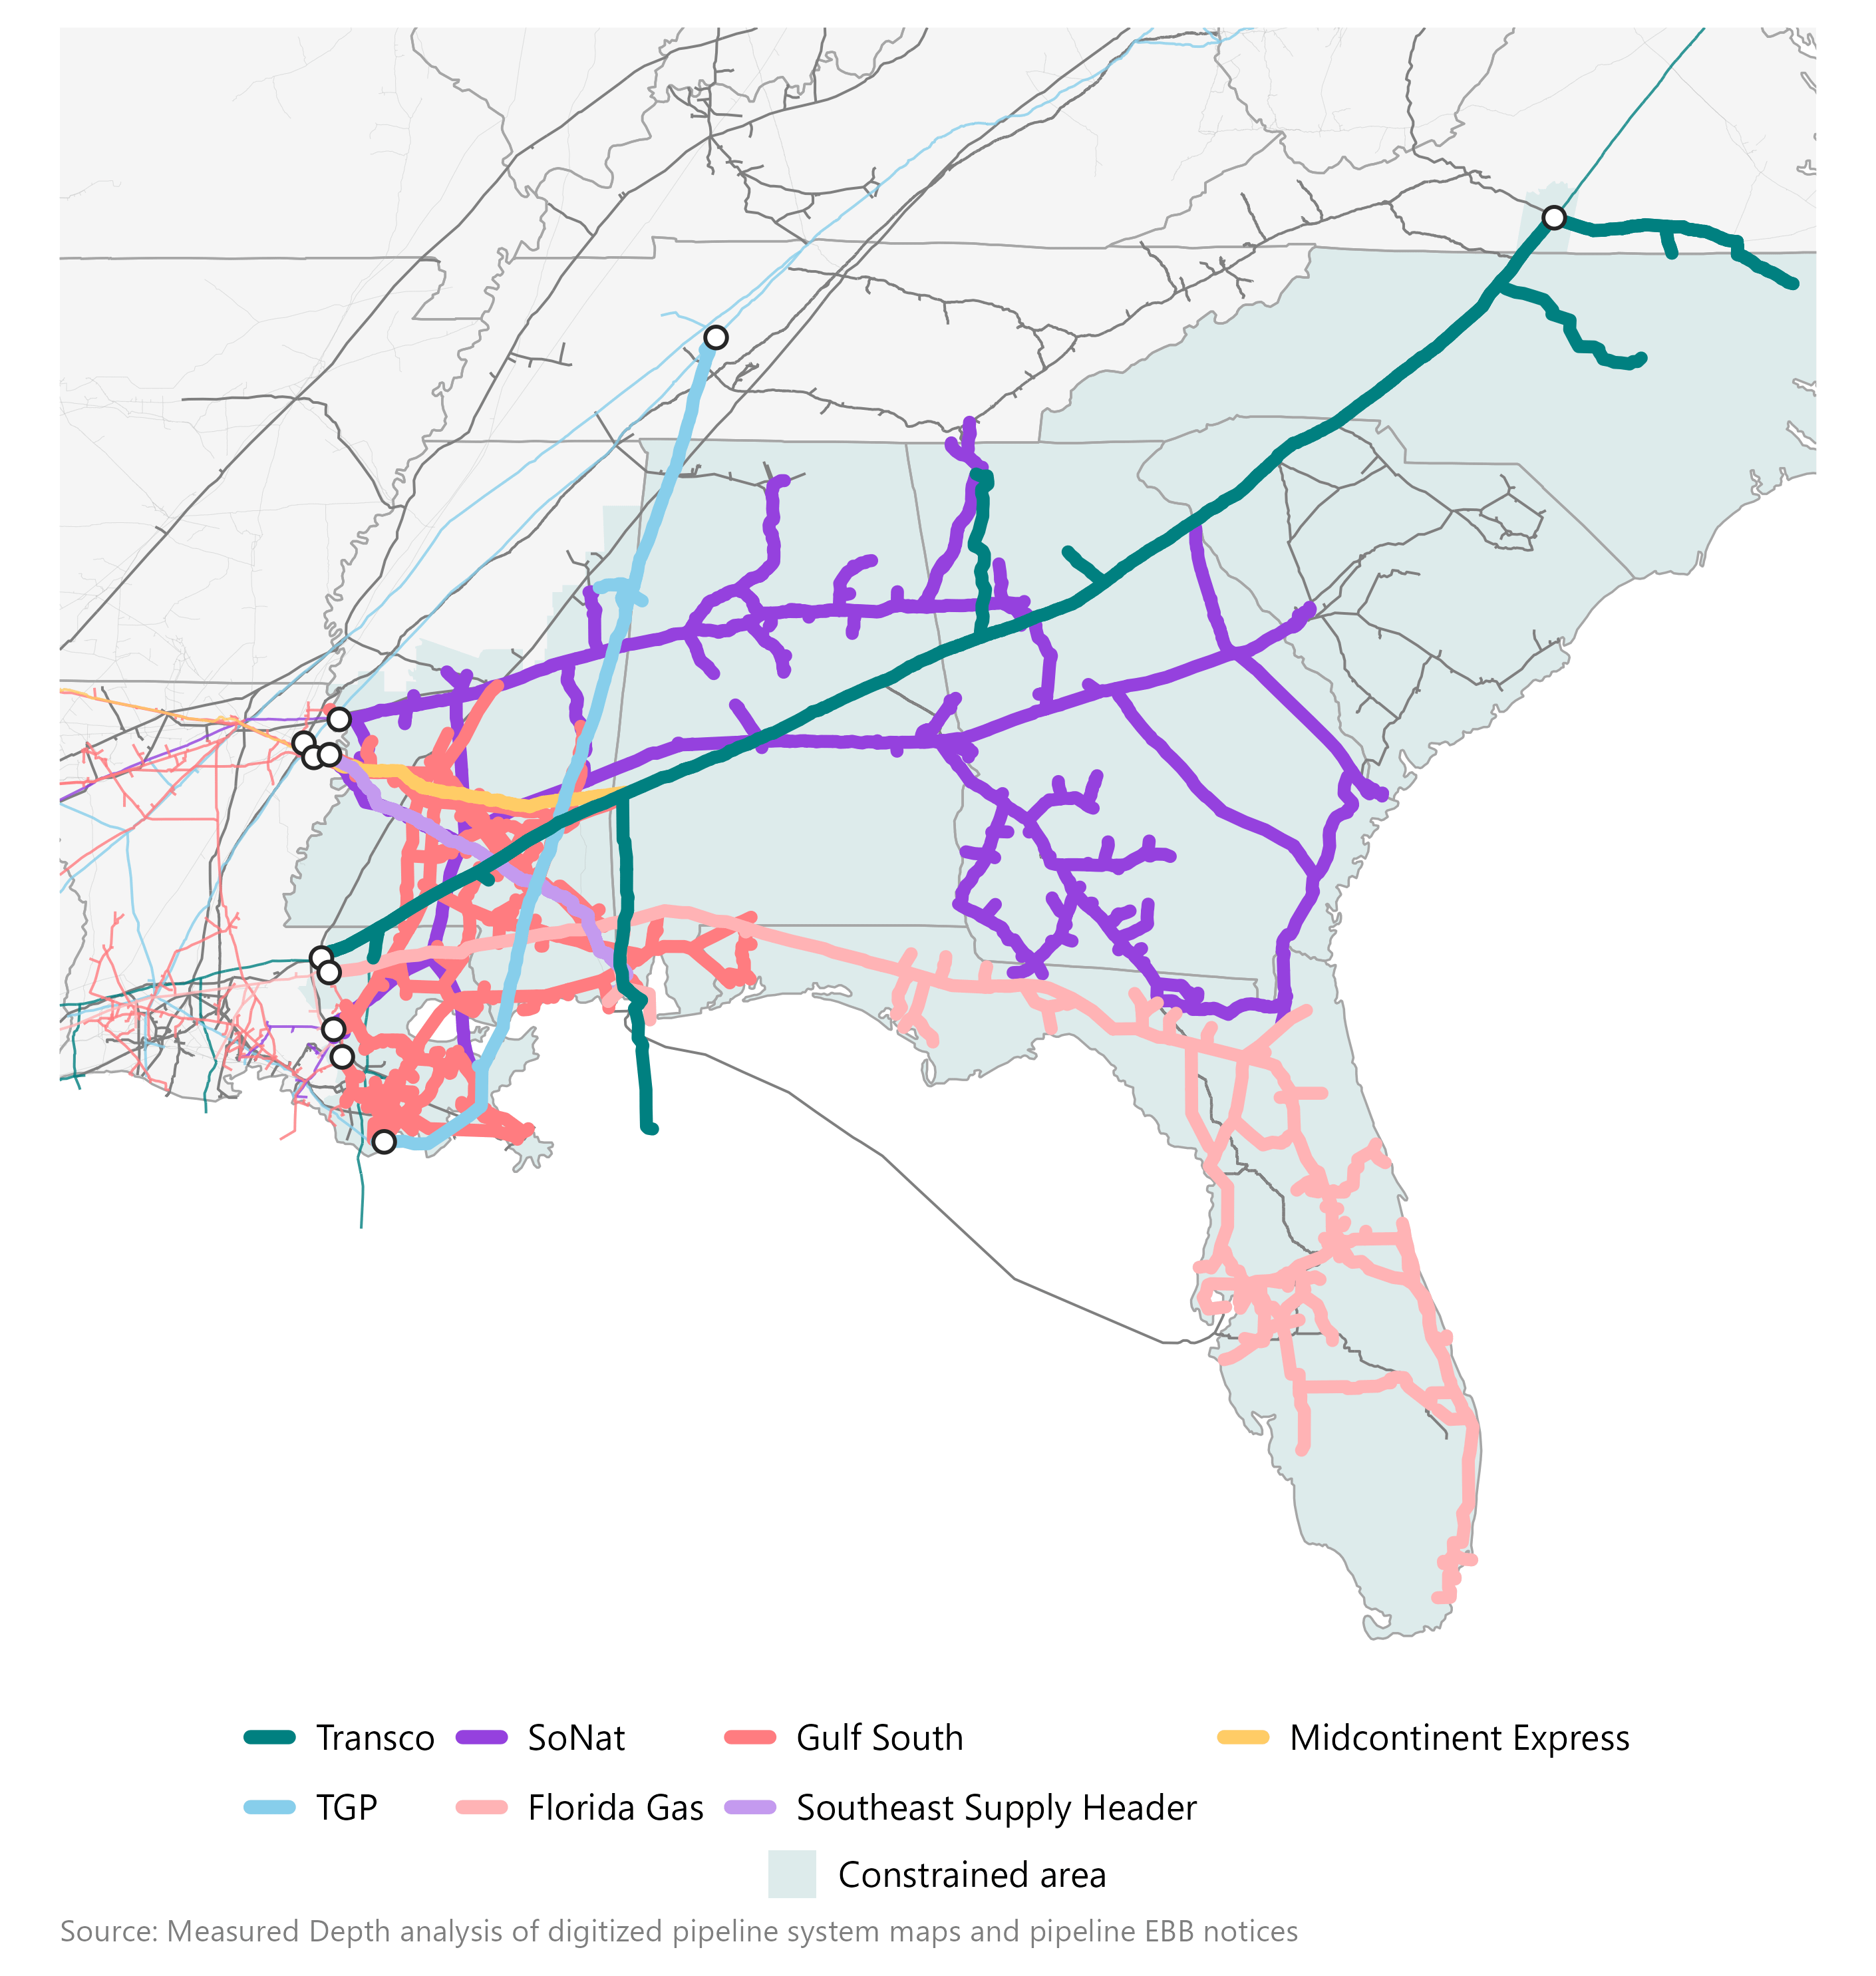
Capacity into the region1 totals ~15 Bcfd across seven major pipeline routes: Transco (from the north and the south), TGP (mostly from the north through Station 860, with small volumes from the south through Station 523), Midcontinent Express, SoNat, Florida Gas, Southeast Supply Header, and Gulf South. Production in the region adds ~1 Bcfd.
Figure 1 | Southeast constrained area and key pipeline routes into the region
Last summer, that capacity comfortably served Southeast demand and refilled storage, with ~900 MMcfd of spare capacity into the region. Two fundamental shifts since then have left the region short: